What is the scope and industry significance of the Battlefield Surveillance System Market?
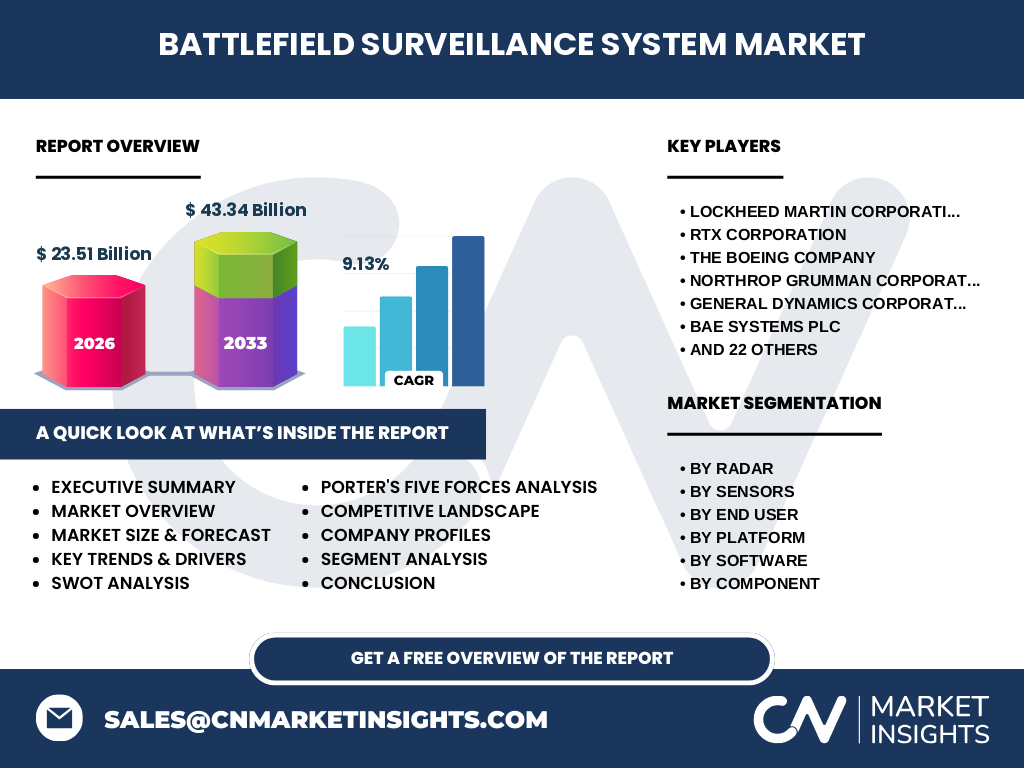
Our proprietary research values the Battlefield Surveillance System Market size at $23.51 billion in 2026, establishing its critical role in modern multi-domain operations. This ecosystem encompasses advanced radars, acoustic sensors, and data fusion software. Prime contractors like Lockheed Martin Corporation and Northrop Grumman Corporation integrate these systems to deliver real-time situational awareness across land, naval, and airborne platforms for defense forces worldwide.
What are the primary growth drivers, restraints, and opportunities shaping the Battlefield Surveillance System Market?
Structural growth in the Battlefield Surveillance System Market industry trends is propelled by rising geopolitical tensions and border security demands. However, stringent ITAR export controls and high R&D costs for hyperspectral imaging create logistical hurdles. Substantial opportunities emerge in autonomous threat detection software deployment, heavily favored by firms like Anduril Industries and Elbit Systems Ltd. to modernize legacy military infrastructure.
Emerging technological trends and growth patterns within the sector
The shift toward artificial intelligence-driven surveillance analytics software is fundamentally transforming battlefield architectures. Unmanned systems technology is rapidly superseding manned platforms, optimizing telemetry and thermal imaging capabilities. Industry innovators such as General Atomics Aeronautical Systems Inc. and AeroVironment Inc. lead this paradigm shift, capturing high-margin defense contracts across contested regional borders.
How did the COVID-19 pandemic impact the Battlefield Surveillance System Market recovery trajectory?
Pandemic-induced supply chain disruptions for critical raw materials like gallium and germanium initially decelerated defense procurement cycles. Nevertheless, our analysis indicates a robust post-pandemic rebound. Government budget reallocations toward resilient, contactless command and control software accelerated long-term modernization roadmaps, reinforcing the market's defensive characteristics against macroeconomic volatility.
Competitive benchmarking and strategic dynamics in the market landscape
The market features high industry concentration among defense primes like RTX Corporation, BAE Systems plc, and Thales Group. Strategic positioning centers on vertical integration, combining proprietary electro-optical sensors with secure data transmission systems. Smaller agile innovators frequently partner with these primes to supply specialized threat detection algorithms, driving continuous technological differentiation.
Executive Summary of the Battlefield Surveillance System Market
Our comprehensive Battlefield Surveillance System Market analysis projects expansion from $23.51 billion in 2026 to $43.34 billion by 2033 at a 9.13% CAGR. Growth is underpinned by surging demand for persistent ground and airborne surveillance radar. Defense agencies prioritize networked architectures, positioning technology leaders with robust multispectral imaging and integration capabilities for sustained outperformance.
Long-term revenue projections and growth trajectory through 2033
Driven by compounding defense modernization investments, the Battlefield Surveillance System Market is forecasted to scale from $23.51 billion in 2026 to $43.34 billion by 2033. This trajectory reflects a steady 9.13% CAGR. Accelerated adoption of naval surveillance radar and counter-battery systems across emerging economies will serve as primary revenue catalysts during this forecast window.
Comprehensive segmentation analysis across platforms, components, and technologies
The ecosystem segments by radar, sensors, software, platform, component, technology, application, and imaging systems. Defense and homeland security end-users rely heavily on land and airborne platforms equipped with night vision and acoustic sensors. Software segments—specifically data fusion and image processing—command expanding budget shares as forces demand automated intelligence filtering.
Geographic distribution and cross-regional performance dynamics
Regional performance varies based on localized defense expenditure priorities and border vulnerability index ratings. North America commands the largest revenue share, supported by federal defense outlays benefiting domestic primes like L3Harris Technologies Inc. Meanwhile, the Asia-Pacific region demonstrates the fastest growth velocity, driven by maritime territorial disputes prompting heavy investments in naval radar and coastal surveillance.
In-depth regional review of key operational theaters
In Europe, cross-border defense cooperation frameworks like PESCO stimulate joint procurement of advanced electronic warfare and surveillance analytics software. Major regional suppliers such as Leonardo S.p.A., Saab AB, and HENSOLDT AG capitalize on localized procurement mandates. Conversely, Middle Eastern markets prioritize turnkey electro-optical imaging and counter-drone sensor networks from providers like ASELSAN A.Ş.
Strategic positioning of leading industry participants
Tier-1 contractors like General Dynamics Corporation and Kongsberg Gruppen ASA leverage global service footprints to secure long-term maintenance contracts. Specialized developers such as Teledyne FLIR LLC focus on high-performance thermal imaging hardware. This diversification allows companies to hedge against shifting defense budget allocations while retaining dominant market positioning.
Porter's Five Forces assessment of industry competitiveness
The threat of new entrants remains low due to prohibitive capital expenditure requirements, rigorous military certification standards, and strict defense export regulations. However, buyer power is moderate to high, as sovereign defense agencies dictate stringent performance specifications, pressuring prime contractors on pricing and proprietary data rights.
SWOT evaluation of the global surveillance ecosystem
Key strengths include unmatched sensor precision and robust multi-domain integration. Weaknesses involve vulnerability to supply chain bottlenecks for rare-earth metals. Opportunities lie in counter-UAS integration, while threats stem from escalating cyber-warfare capabilities targeting command and control software links.
Value chain analysis from raw material inputs to end-user deployment
The value chain originates with raw material providers supplying semiconductor wafers and optical glass. Mid-tier component manufacturers fabricate specialized radar transceivers and infrared sensors, which systems integrators assemble into cohesive platforms. End-users deploy these assets via defense ministries, relying heavily on ongoing maintenance and software support equipment.
Strategic investment insights and high-potential market segments
Our analysis highlights surveillance analytics software and unmanned systems technology as high-yield investment corridors. Investors should target nimble tech firms specializing in AI-driven threat detection algorithms. Primes seeking inorganic growth frequently acquire these niche innovators to enhance their proprietary digital battlefield offerings.
Conclusion and key strategic takeaways for market stakeholders
The Battlefield Surveillance System Market is poised for accelerated expansion, reaching $43.34 billion by 2033. Stakeholders must prioritize software-defined architectures and modular sensor integration. Companies failing to adapt to autonomous, multi-domain networked warfare risk obsolescence amid rapidly evolving military requirements.
Methodological framework and data triangulation processes
Baseline market estimates are established by triangulating primary stakeholder interviews with defense attachés, procurement executives, and tier-1 engineering leads. This qualitative intelligence is cross-referenced against secondary macroeconomic indicators, defense budgetary registries, trade association filings, and historical shipment volumes to ensure high data fidelity.
Report scope, coverage parameters, and analytical limitations
This report covers global revenue performance across all major segments from 2026 to 2033. Excluded from the scope are non-military commercial security systems and localized civil aviation radars. Macroeconomic fluctuations and unforeseen geopolitical shifts represent inherent analytical limitations within the forecast model.
Recent strategic developments, partnerships, and product launches
Recent industry momentum is defined by strategic joint ventures, such as co-development agreements for quantum radar and advanced optical sensors. Notable contract awards to firms like CACI International Inc and Cubic Corporation underscore the accelerating pivot toward cloud-enabled tactical networks and resilient, jam-resistant data transmission systems.